
本文暂无中文版本,现显示英文原文。
BoG orders banks to slash bad loan ratios below 10% by end of 2026
The Bank of Ghana (BoG) has issued a firm directive to all regulated financial institutions to reduce their Non-Performing Loan (NPL) ratios to below 10 percent by December 2026, in a decisive move to unlock credit to the real economy and fortify the banking sector against future shocks. The Governor of the central bank, Dr.…
发布于 阅读约 3 分钟
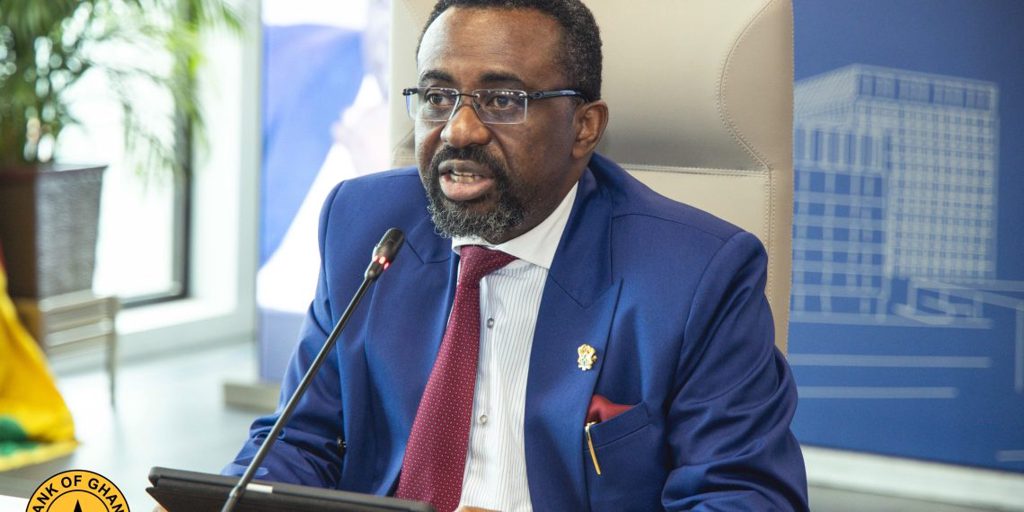
The Bank of Ghana (BoG) has issued a firm directive to all regulated financial institutions to reduce their Non-Performing Loan (NPL) ratios to below 10 percent by December 2026, in a decisive move to unlock credit to the real economy and fortify the banking sector against future shocks.
The Governor of the central bank, Dr. Johnson Pandit Asiama, announced the target during a forum in Accra on “Restructuring Distressed Companies: Non-Performing Loans (NPLs) and Post-Commencement Financing,” organised to address the persistent drag of bad loans on economic growth.
While acknowledging recent improvements in asset quality, Dr. Asiama stressed that the current NPL level remains a serious impediment to the sector’s ability to extend credit to businesses and households, particularly small and medium-sized enterprises (SMEs) that form the backbone of Ghana’s economy.
Progress, but not enough
The Governor disclosed that the industry’s NPL ratio had declined to 16.1 percent as of June 2026, down from 23.1 percent recorded in June 2025. The Capital Adequacy Ratio (CAR) also strengthened considerably, rising to 20.4 percent from 10.6 percent over the same period, giving banks greater room to absorb losses.
“Capital at that level gives banks the room to take considered risks,” Dr. Asiama noted. “But while this represents progress, it is not sufficient.”
He emphasised that the central bank would not rest on the modest gains, and directed each institution to submit credible NPL reduction plans, strengthen credit appraisal systems, and write off fully provisioned exposures with no realistic prospect of recovery.
“The industry’s non-performing loan ratio has declined to 16.1 percent as of the end of June this year, down from over 23 percent a year ago. But our regulatory measures require every regulated institution to reduce its NPL ratio to no more than 10 percent by the end of December this year,” he said.
Wider economic implications
Dr. Asiama explained that high NPLs are not merely a supervisory headache but a direct threat to national development, because they tie up bank capital, increase recovery costs, and restrict new lending—most severely affecting smaller and higher-risk borrowers.
“Reducing them is therefore not merely a supervisory concern. It is part of Ghana’s development agenda,” he added.
The directive comes against a backdrop of robust growth in the banking industry. Total assets expanded by 30.7 percent year-on-year to GH¢502.4 billion in June 2026, supported by growth in deposits, borrowings and shareholders’ funds. However, bankers have long complained that the high NPL burden has constrained their appetite for new lending, stifling job creation and investment.
Background and sector context
The NPL problem has dogged Ghana’s banking sector since the 2017–2018 financial sector clean-up, which saw the revocation of licences of several insolvent banks and specialised deposit-taking institutions. While the clean-up restored confidence, legacy bad loans continued to weigh on balance sheets, exacerbated by the economic fallout from the COVID-19 pandemic and the recent domestic debt restructuring programme.
The 10 percent threshold, if achieved, would bring Ghana closer to the prudential benchmark of 5 percent considered healthy in many emerging markets. Industry analysts have welcomed the target but cautioned that achieving it will require a combination of aggressive loan recovery, judicial reforms to expedite collateral enforcement, and improved corporate governance among borrowers.
The BoG has indicated that it will monitor compliance quarterly and apply sanctions for non-adherence, including higher capital requirements and restrictions on dividend payments.
The engagement with banks and distressed companies is expected to continue in the coming months, with the central bank positioning itself as a facilitator of loan restructuring and post-commencement financing to salvage viable but ailing businesses.
As the December 2026 deadline approaches, all eyes will be on the banking sector to see whether the new target becomes a turning point—or another missed opportunity—in Ghana’s quest for sustained, credit-driven economic growth.
订阅 AfroAsia Media 新闻简报
每日非洲与亚洲要闻,直接发送到您的邮箱。



评论
0 条评论
加载中…