
我们正在将本文翻译成中文,译文稍后将显示在此处。目前先显示英文原文。
Banks’ profit dip to GHc7.1bn as falling interest rates squeeze earnings
Ghana’s banking industry remained profitable in the first half of 2026, but earnings came under significant pressure as the low interest-rate environment weighed heavily on banks’ core income, according to the Bank of Ghana’s July 2026 Monetary Policy Report . The industry’s profit-after-tax fell marginally to GH¢7.1 billion at end-June 2026, from GH¢7.2 billion a…
发布于 阅读约 4 分钟
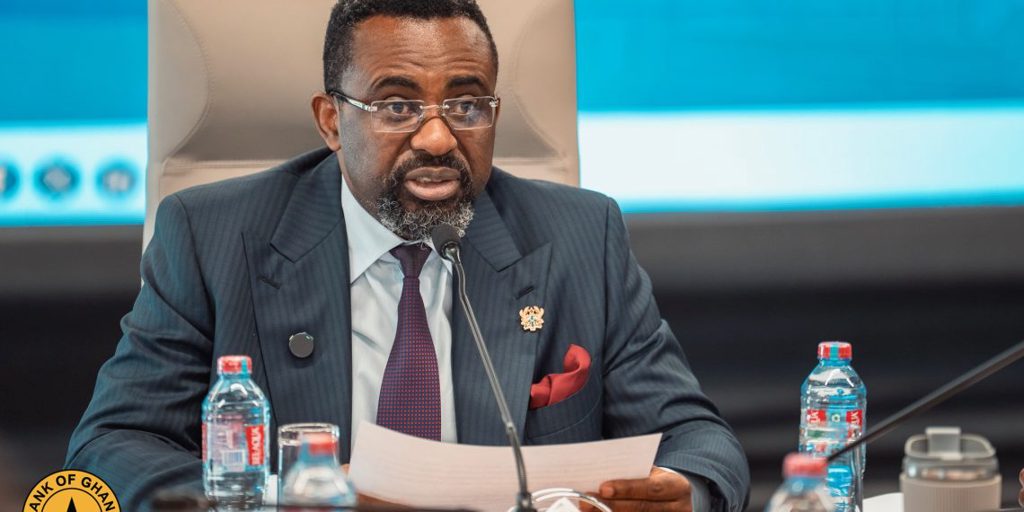
Ghana’s banking industry remained profitable in the first half of 2026, but earnings came under significant pressure as the low interest-rate environment weighed heavily on banks’ core income, according to the Bank of Ghana’s July 2026 Monetary Policy Report .
The industry’s profit-after-tax fell marginally to GH¢7.1 billion at end-June 2026, from GH¢7.2 billion a year earlier—a 1.3% contraction that marks a sharp reversal from the 32.6% growth recorded in June 2025 . Profit-before-tax also declined by 1.5%, compared with a 32.2% expansion a year earlier .
Interest income under pressure
The biggest drag on profitability came from net interest income, which contracted by 3.1%—reversing a 20.2% growth recorded in June 2025 . The Bank of Ghana attributed the slowdown largely to the prevailing low interest-rate environment, which has reduced returns from loans and other interest-generating investments .
The Ghana Reference Rate, the benchmark used by commercial banks to price cedi-denominated loans, declined to 10.18% in September 2026 from 23.80% a year earlier—a 57% drop within 12 months . Average lending rates have fallen from around 27% a year ago to about 15%, providing relief to borrowers but squeezing banks’ interest income .
Investment income remained banks’ largest source of earnings, although its contribution to total income fell to 42.8% from 46.4% . Income from loans and advances also declined as a share of total income, from 30.1% to 28.4% .
Fee income provides some relief
Despite the pressure on interest income, banks recorded stronger growth in income from fees and commissions, which increased by 18.2%—slightly above the 17.8% growth recorded a year earlier . The increase provided some support to banks’ overall earnings but was not enough to offset the decline in net interest income .
Banks also exercised greater control over their operating expenses during the period, with operating expenses increasing by 6%—significantly lower than the 21.4% growth recorded a year earlier . The slower increase helped cushion some of the pressure on profitability.
Rising provisions weigh on bottom line
The sector faced a significant increase in provisions for bad debts and impairment-related costs. Provisions for depreciation, bad debts, and impairment losses on financial assets surged by 38.2%, compared with a 14.8% contraction in June 2025 .
The sharp rise indicates increased pressure from credit-related and other financial losses, further weighing on banks’ bottom-line performance . However, industry-wide data shows the non-performing loan ratio has declined to 16.1% from 23.1% a year earlier , suggesting the increase in provisions may reflect a more conservative provisioning stance rather than deteriorating asset quality.
Profitability indicators weaken
The moderation in profitability was reflected in key performance indicators. Return on Equity fell sharply to 22.9% from 32.2%, while Return on Assets declined to 4.4% from 5.6% . The industry’s interest spread narrowed to 4.4% from 6.0%, while gross yields dropped to 6.1% from 8.9% .
Individual bank performance varies
Despite the industry-wide pressure, some banks have demonstrated resilience. GCB Bank reported a profit after tax of GH¢1.23 billion for the first half of 2026—a 46.4% increase over the corresponding period last year . The bank weathered the lower interest rate environment by reducing funding costs and significantly expanding income from fees, commissions, and trading activities . Net fee and commission income nearly doubled, increasing by 98% to GH¢658.7 million .
Private sector credit expands
The lower interest rate environment has encouraged increased lending to the private sector. Private-sector credit expanded 41.2% year-on-year in June 2026, compared with growth of 8.6% in June 2025 . Total bank advances increased to GH¢124.3 billion in June 2026 from GH¢89.7 billion a year earlier, representing growth of 38.6% .
Bank of Ghana Governor Dr Johnson Pandit Asiama has urged banks to increase financing to the productive sectors as monetary conditions improve, with particular attention to small and medium-sized enterprises and agriculture . However, agriculture and manufacturing continue to receive relatively small portions of private-sector credit despite their role in government’s industrialisation and export programmes .
Outlook
The latest performance suggests Ghana’s banking sector is moving from the strong profit growth recorded in 2025 to a period of more moderate earnings . While banks continued to generate significant profits, the combination of lower interest income and higher provisions limited overall growth .
The Bank of Ghana expects the banking sector to remain stable, with the outlook depending on banks continuing to follow strict lending rules and managing risks effectively . Credit to businesses and households is likely to increase in the coming months, especially as monetary policy eases, which could support economic growth across the country .
订阅 AfroAsia Media 新闻简报
每日非洲与亚洲要闻,直接发送到您的邮箱。



评论
0 条评论
加载中…