
BoG to Scrutinise 2027 Budget Financing for Inflation, Cedi Risks as Final MPC Meeting Opens
The Bank of Ghana has put the government’s 2027 Budget under the microscope, with Governor Dr Johnson Asiama directing the Monetary Policy Committee to scrutinise the financing arrangements and…
Journalist
Published 4 min read
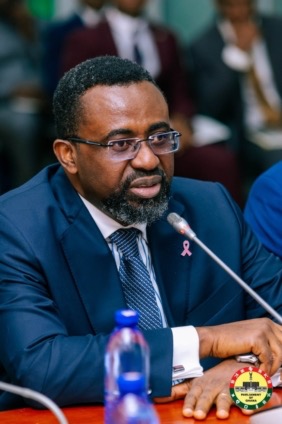
The Bank of Ghana has put the government’s 2027 Budget under the microscope, with Governor Dr Johnson Asiama directing the Monetary Policy Committee to scrutinise the financing arrangements and expenditure plans of the GH¢389.2 billion budget for their potential to reignite inflation, distort liquidity and destabilise the cedi.
Speaking at the opening of the 133rd MPC meeting at the Bank Square on Monday, November 16, 2026—the final gathering of the year and the one that will set the policy direction going into 2027—Dr Asiama said the Committee would assess the budget’s fiscal impulse at what he described as an important point in Ghana’s economic recovery, as the government pivots from stabilisation towards productive investment and growth.
“The committee will need to carefully assess the size and composition of the fiscal surplus, its financing arrangements, and the likely implications for aggregate demand, for liquidity, for inflation, and for the exchange rate,” Dr Asiama said.
The Fiscal Numbers Under Review
The budget, presented by Finance Minister Dr Cassiel Ato Forson on November 12, projects total revenue and grants of GH¢323.4 billion (17.9 per cent of GDP) against expenditure of GH¢389.2 billion (21.6 per cent of GDP), leaving an overall cash deficit of GH¢65.8 billion, equivalent to 3.6 per cent of GDP. The primary surplus target has been cut from 1.5 per cent of GDP in 2026 to 0.5 per cent in 2027—a deliberate relaxation of fiscal consolidation to free resources for the government’s US$10 billion New Economy programme.
That programme, which targets agriculture, energy, manufacturing and minerals processing, is allocated GH¢30 billion (about US$2.6 billion) in 2027 alone. The government insists the initiative will be financed from domestic resources rather than fresh external borrowing, with the lower primary surplus target freeing up the equivalent of one percentage point of GDP. The plan is to cover the resulting larger deficit mainly through domestic borrowing.
It is precisely that domestic financing requirement—and the timing and distribution of government spending—that the MPC has flagged as the central risk. Dr Asiama said the timing and distribution of public expenditure would be critical in determining liquidity conditions within the financial system, and the Committee would examine whether fiscal operations could undermine the gains achieved in stabilising the economy.
A Delicate Policy Moment
The scrutiny comes at a sensitive juncture. Headline inflation, which fell sharply from 23.8 per cent in December 2024 to 5.4 per cent in December 2025, edged up to 5.5 per cent in October 2026 from 5.2 per cent in September. The MPC had cut the policy rate by 250 basis points to 15.5 per cent in January 2026, then by a further 150 basis points to 14 per cent in March, and has held at 14 per cent through May, July and September. The Committee must now decide whether the recent uptick reflects temporary price adjustments or more persistent pressures, with particular attention to food, non-food and services inflation, and inflation expectations.
Dr Asiama also flagged the potential impact of an unusually strong El Niño episode on agricultural production, food prices, cocoa output and export earnings into the first quarter of 2027—a risk that could strike simultaneously at inflation and the exchange rate by raising food costs and reducing foreign exchange inflows.
Reserves, the Cedi and the Five-Point Review
The MPC’s agenda extends beyond the budget. The Committee is assessing five key areas: the global economic environment and exchange rate developments; domestic inflation and economic conditions; external sector performance and reserve accumulation; fiscal developments and the 2027 Budget; and the effectiveness of monetary policy transmission.
On the external sector, the Governor urged the Committee to look beyond the headline current account surplus to the sustainability of inflows and reserve accumulation. Ghana’s gross international reserves reached US$12.7 billion at the end of September 2026, equivalent to about 4.5 months of import cover—a marked improvement from the crisis years but still short of the 5.7 months the Finance Minister has cited in other contexts.
On monetary transmission, the Bank will conduct a comprehensive review of how effectively its policy decisions feed through money-market conditions, bank funding costs and lending rates to private sector credit and economic activity, and whether the existing operational framework provides a clear policy signal and supports efficient liquidity management.
The Coordination Imperative
Dr Asiama was emphatic that the objective is not to second-guess the budget but to ensure coherence between the fiscal and monetary arms of policy.
“The objective is to ensure that the fiscal and monetary policy frameworks remain coherent and mutually reinforcing in preserving macroeconomic stability,” he said.
For a central bank that has spent 2026 consolidating hard-won gains—single-digit inflation, a stable currency, declining borrowing costs and rising reserves—the 2027 Budget represents the first real test of whether the government can spend ambitiously without spending recklessly. The MPC’s verdict, expected on Wednesday, will signal whether the Bank believes the fiscal impulse can be absorbed smoothly, or whether the policy rate must rise to keep inflation and the cedi anchored as Ghana enters an election-year budget cycle.
Get the AfroAsia Media newsletter
The day's top stories from Africa and Asia, straight to your inbox.
Comments
0 comments
Loading…