
BoG defends microfinance reforms amid industry concerns over costs and timelines
The Bank of Ghana (BoG) has firmly defended its comprehensive overhaul of the microfinance and specialised deposit-taking institutions (SDI) sector, insisting that the reforms are essential for rebuilding public confidence, strengthening financial institutions, and addressing long-standing vulnerabilities. The central bank’s position comes as industry players raise concerns about implementation timelines and the financial burden of…
Published 4 min read
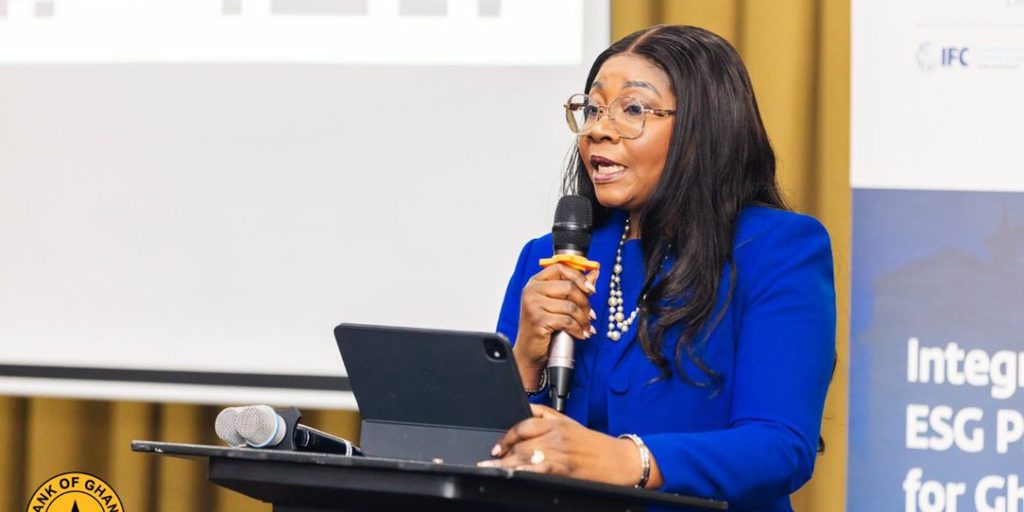
The Bank of Ghana (BoG) has firmly defended its comprehensive overhaul of the microfinance and specialised deposit-taking institutions (SDI) sector, insisting that the reforms are essential for rebuilding public confidence, strengthening financial institutions, and addressing long-standing vulnerabilities. The central bank’s position comes as industry players raise concerns about implementation timelines and the financial burden of compliance.
Speaking at the 16th Annual General Meeting of the Ghana Association of Savings and Loans Companies (GHALSAC) in Accra, Second Deputy Governor of the Bank of Ghana, Matilda Asante-Asiedu, addressed the sector’s key stakeholders directly .
“This reform is not merely about introducing stricter regulations. It is about rebuilding public confidence and trust,” she stated, framing the changes as a foundational reset for the industry rather than a punitive exercise .
The Three Pillars of Reform
The reforms, which replace the previous fragmented Tier 1-4 structure, focus on three critical areas: capital adequacy, governance and risk management, and structural restructuring . Asante-Asiedu explained that revised capital requirements are designed to enable institutions to absorb losses and withstand economic shocks, while higher governance and risk management standards will strengthen oversight across the sector .
The structural reform includes the conversion of all 147 rural banks into Community Banks, a move the central bank says will modernise a subsector that has served as a cornerstone of financial inclusion for five decades. These institutions, with nearly 1,000 branches nationwide serving over eight million customers, must complete rebranding and regulatory alignment by December 2026 .
Under the new framework, the sector will be organised into four categories: Microfinance Banks, Community Banks, Credit Unions, and Last-Mile Providers .
Acknowledging Industry Concerns
Asante-Asiedu was candid in acknowledging the concerns raised by industry players regarding the pace and practical implications of the transition.
“Based on our engagement with the association, we took note of concerns about the timelines, transition arrangements and other aspects of the reforms,” she said, adding that technical teams from the Bank and the association have been established to resolve outstanding issues .
The central bank is also preparing additional regulations, including corporate governance and risk management guidelines, which will be published for industry comment .
The Cost of Reform
The Second Deputy Governor offered a rare and candid admission of the burdens the transition places on institutions.
“We recognise that reform is never costless. Compliance costs, operational adjustments and new regulatory expectations are real burdens, and the Bank of Ghana does not take them lightly,” she said .
She maintained, however, that the long-term benefits outweigh the immediate pressures. Properly implemented reforms, she argued, will strengthen confidence, deepen financial inclusion, and support greater local participation in the financial sector .
Sector Performance and the NPL Challenge
The reforms come at a critical juncture for the sector. Industry data presented at the AGM revealed the significant role microfinance institutions play in Ghana’s economy. According to Finance Minister Dr Cassiel Ato Forson, whose speech was read on his behalf at the event, the microfinance sector serves more than 19 million Ghanaians, supports over 40,000 direct jobs, manages assets exceeding GH¢50 billion, and provides loans of more than GH¢20.5 billion to households and businesses .
However, the sector faces a significant challenge with non-performing loans (NPLs). The Bank of Ghana has directed all regulated financial institutions to reduce their NPL ratios to no more than 10% by December 2026, with microfinance institutions facing a stricter 5% ceiling . Failure to meet these targets could result in regulatory restrictions, including bans on dividend payments and limitations on loan portfolio expansion from January 2027 .
The Association of Savings and Loans Companies has committed to working to bring the sector’s NPL ratio within the target set by the central bank .
Industry Response
GHALSAC CEO Tweneboah Kodua Boakye said the association supports the intent of the reforms but wants the transition to be “orderly, realistic and sensitive to the role of microfinance institutions” . He identified financial inclusion, digital transformation, MSME financing, and partnerships as major opportunities for the sector, urging institutions to invest in technology and strengthen governance .
The Ghana Association of Savings and Loans Companies has also shown strong financial health, reporting an 89% surge in total income to GH¢1.84 million in 2025 from GH¢972,207 in 2024, demonstrating the sector’s capacity for growth even amid regulatory change .
Broader Agenda
Asante-Asiedu’s remarks come as the central bank pursues a broader agenda to strengthen Ghana’s financial architecture. In separate remarks earlier this month, she highlighted the need to address the SME financing gap, estimated at about US$4.8 billion annually . She noted that Ghana’s challenge is not a capital shortage but an “architecture problem,” urging lenders to make greater use of digital transaction data when assessing borrowers .
As the reforms take shape, the central bank’s message to the industry is clear: the transition may be demanding, but the destination—a more resilient, inclusive, and trustworthy financial sector—is worth the journey.
Get the AfroAsia Media newsletter
The day's top stories from Africa and Asia, straight to your inbox.



Comments
0 comments
Loading…